

Debt Payoff Planner & Tracker

- 1.23K Reviews
- 4.5
- Downloads
- 500,000+
Our take on Debt Payoff Planner & Tracker from Appgk
Debt is rarely difficult because people cannot do basic arithmetic. It is difficult because several balances, interest charges, due dates, and competing priorities create a problem that feels too large to hold in your head. I found Debt Payoff Planner & Tracker most useful at that uncomfortable starting point: when I knew I wanted a plan, but needed something more concrete than a promise to “pay extra when possible.” It turns the debt journey into a sequence of decisions that I can review instead of an abstract worry.
This is a free finance app from Easily get a plan and stick to it - OxbowSoft LLC, built around the idea of planning, tracking, and celebrating progress. Its store short description is simply “Debt Payoff Planner,” but that undersells the practical value. The app is not a bank account, a lender, or a replacement for a full household budget. I see it as a focused planning layer: a place to organize debts, choose a payoff approach, and keep the target visible while the actual payments still happen through my bank or creditor.
The app has earned a 4.5 average from around 4.7 thousand ratings, with more than 500 thousand installs. Those figures suggest it has found a clear audience among people who want a dedicated debt tool rather than a broad money-management suite. It is rated Everyone, so its subject matter is serious without making the app unsuitable for general audiences. It runs on Android from version 6.0 onward, and the current version is 2.54.
From an uncomfortable debt pile to a workable routine
Starting with the information that actually matters
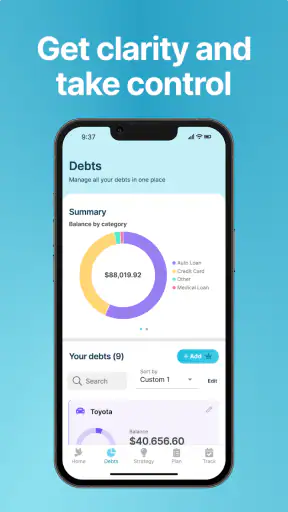
The first useful step is not choosing a payoff method. It is gathering honest starting information. I would open the app with recent statements nearby and record each debt carefully: the balance, the interest rate, and the minimum payment or other details the planner asks for. This is where the quality of the final plan is decided. If I enter an old balance or guess at a rate, the schedule may look reassuring while quietly drifting away from reality.
Best Parts of Debt Payoff Planner & Tracker
Things to Keep in Mind About Debt Payoff Planner & Tracker
That makes the app especially helpful for someone with several credit cards, personal loans, or other balances that are easy to mix up. Instead of keeping a note with scattered figures, I can give every debt a clear place in the plan. The benefit is not just neatness. A named, visible list makes it easier to notice which balance is shrinking and which one is barely moving.
I would still treat the initial setup as a short financial audit rather than a casual form. Statements can include fees, promotional rates, or changes that affect the calculation. The planner can organize the information I provide, but it cannot know whether I copied a figure incorrectly. My practical tip is to enter the debts in one sitting, then compare the resulting list with the statements before committing to a payoff routine.
News and Features Related to Debt Payoff Planner & Tracker

News
YouTube Turns a Quick Video Check Into an Hour of Watching

News
BeautyPlus Makes Portrait Retouching Feel Like Your Own

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo
Choosing a strategy instead of relying on motivation
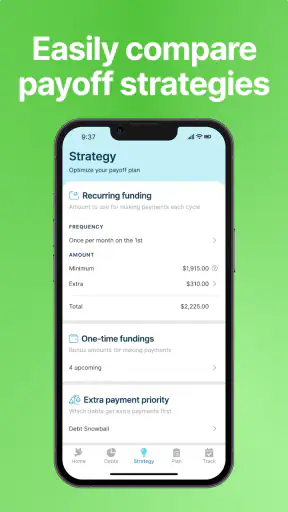
Once the debts are entered, the important decision is how to direct extra money. A payoff planner is valuable because it turns that choice into a visible strategy. Rather than sending occasional extra payments wherever I happen to feel most motivated, I can decide which balance receives the strongest attention while the others remain part of the plan.
There is a real trade-off here. A strategy that prioritizes the most expensive debt can make mathematical sense, while a strategy that targets a small balance first may create an earlier emotional win. Debt Payoff Planner & Tracker is most useful when I choose deliberately and then follow the choice consistently. I would not switch methods every time one account looks more annoying; that creates noise and makes the projected finish harder to interpret.
Don't want to read the full review?
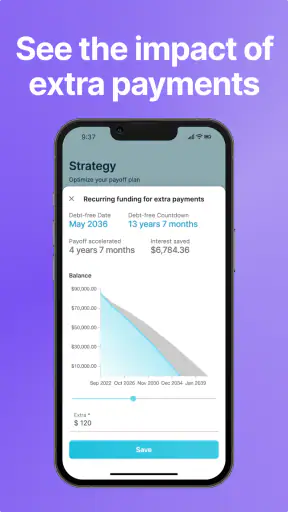
A less obvious advantage is that planning exposes the cost of irregular payments. If I can afford a fixed extra amount each month, the app gives me a clearer target than “pay more whenever I can.” If my income varies, I can use the plan as a baseline and decide in advance how windfalls or unusually good months will be handled. That prevents extra money from disappearing into unrelated spending before I make the decision.
Turning the plan into an everyday payment habit
The app does not remove the need to make payments through the normal creditor or banking channels. That handoff is important: the planner tells me what I intend to do, while the lender’s website or app is where the payment is actually submitted. I would therefore use Debt Payoff Planner & Tracker immediately before paying, not as a substitute for checking the creditor’s current minimum, due date, or confirmation.
Screenshots
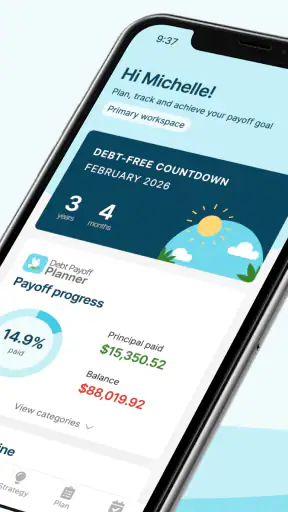
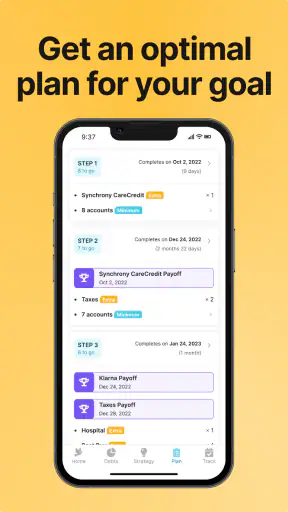
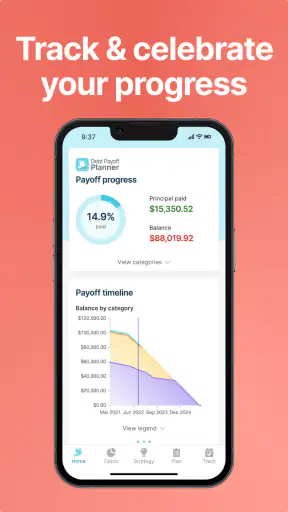
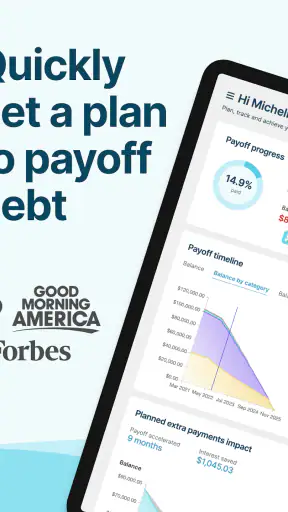
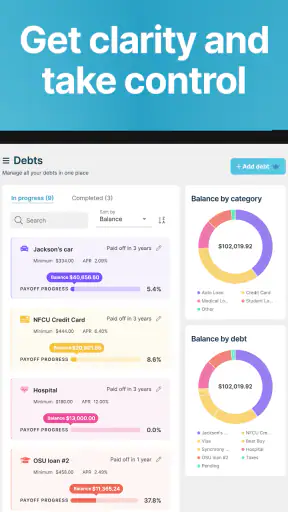
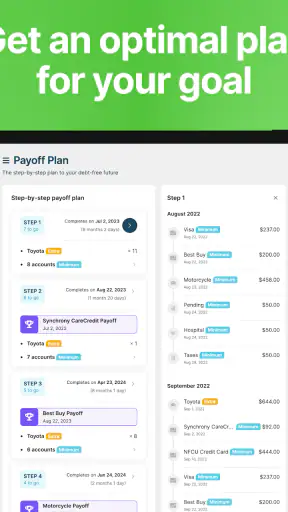
A realistic routine could look like this. On payday, I review the planner and identify the extra amount available after essentials. I check the creditor accounts for updated balances and minimums, then make the required payments through those accounts. Any planned extra payment goes to the priority debt. After the transactions settle, I return to the planner and update the balances so the next projection is based on a current starting point.
That sequence sounds simple, but the handoff is where many financial apps become less useful than expected. A planning tool can be motivating while still requiring manual discipline. I appreciate that separation because it keeps the app focused, but I would not recommend it to someone expecting automatic account syncing or one-tap payments. The person using it has to maintain the bridge between the plan and the real accounts.
Using progress as feedback rather than a reward screen
The tracking side matters because debt repayment is a long project. A balance can fall for months without feeling dramatically different in daily life. Seeing progress in one place gives me a reason to revisit the plan when motivation fades. The celebration element is not a substitute for financial accuracy, but it can make a repetitive task feel less punishing.
My preferred way to use that feedback would be to review progress on a fixed schedule, perhaps around the same time as a monthly money check-in. Looking at the tracker every day could encourage unnecessary anxiety, especially when interest or pending transactions make balances move in small, confusing ways. A scheduled review keeps the app in its proper role: a decision aid and accountability tool, not a source of constant financial monitoring.
Another useful workflow is to record why the plan changed. If I lower an extra payment because of a car repair or raise it after a temporary income boost, I would make a short note outside the app or in my personal budget records. The planner shows the updated direction, but the reason helps me distinguish a deliberate adjustment from simply losing momentum. That distinction is valuable when I look back later.
What the result looks like in practice
The result is not instant debt freedom. The result is a clearer answer to three practical questions: which debt receives attention, how much I intend to pay, and whether the balances are moving in the direction I expected. That clarity can make a complicated situation feel manageable without pretending it is easy.
For example, imagine someone with a few balances and a limited amount left after rent, food, utilities, and minimum payments. The planner helps turn that remaining amount into a repeatable instruction. Instead of dividing it randomly or leaving it unspent, the person can direct it according to the selected plan, update the balances after payments, and see whether the expected progress still matches reality. If the result is too slow, the problem becomes visible enough to discuss: reduce spending, increase income, change the extra payment, or seek outside advice.
This is where I think the app is stronger than a spreadsheet for many people. A spreadsheet can be more flexible, but it also asks the user to design formulas, maintain layouts, and decide how to visualize progress. Debt Payoff Planner & Tracker offers a narrower experience built around the debt problem itself. That narrowness is a strength when I want guidance and momentum rather than a custom financial model.
Where the workflow breaks down
The same focus that makes the app approachable also creates limits. It is not the right choice if I need a complete household budget covering bills, spending categories, savings goals, investments, and shared accounts in one connected system. A general budgeting app or a carefully designed spreadsheet may be better for someone whose main problem is cash-flow management rather than debt prioritization.
The manual handoff can also become a source of error. If I forget to update a balance, make a payment from a different account, or receive a fee that changes the total, the plan can become stale. I would never use an old projection to decide that a creditor payment is safe. The creditor account remains the authority for current obligations; this app is the place where I organize my intended payoff path.
Variable interest rates and changing minimum payments can make projections less stable too. A plan is most useful as a direction, not a guarantee. I would revisit the figures after major account changes, promotional periods, fees, or any month when the payment does not go through as expected. That small habit prevents the comforting chart from becoming misleading.
There is also a motivational limitation. Seeing a plan does not solve the reason debt accumulated, and it cannot create money that is not available. Someone facing missed essentials, collection pressure, or an income crisis may need a nonprofit counselor or another qualified source of help before optimizing payoff order. In that situation, a tracker can support the conversation, but it should not be mistaken for professional financial advice.
Who will get the most from it
I would recommend it to a person who has enough income to make required payments and wants a dedicated way to attack multiple debts. It suits users who benefit from a visible target, prefer a guided debt workflow, and are willing to update information after payments. It is also a good fit for someone who has tried vague intentions and needs a concrete routine that can be repeated each month.
It may be particularly useful for couples or households that need a shared conversation, even if only one person maintains the plan. Sitting down together to review the debt list and agree on where extra money goes can reduce arguments caused by different assumptions. The app does not replace communication, but it gives that conversation a common structure instead of relying on memory.
I would skip it if I have only one simple balance and already understand exactly how I will repay it, or if I need automatic synchronization with financial institutions. I would also look elsewhere if I want advanced reporting, a full budget, or detailed tax and investment tools. The best alternative depends on the problem: a spreadsheet for maximum control, a broad budgeting app for household cash flow, or professional guidance when repayment is not currently affordable.
Cost, access, and what to expect before committing
The app is free to download and use as a finance tool, with optional in-app purchases ranging from $6.99 to $41.99 per item. I would begin with the free experience and decide whether the planning workflow genuinely fits my habits before paying for anything. The existence of optional purchases means I would check the exact feature or duration attached to an item on the platform before confirming it, rather than assuming every part of the experience is included.
Its Everyone rating makes it easy to recommend as a general-purpose debt organization tool, but age suitability should not be confused with financial suitability. A younger user may understand the interface while still needing an adult or counselor to help interpret interest, contracts, and repayment priorities. The app can make the numbers easier to arrange; it cannot replace financial judgment.
Compatibility is also straightforward for Android users with a device running version 6.0 or later. That broad support is convenient, although I would still keep a personal backup of the starting balances and payment records. Any planning app is most valuable when the information remains recoverable if I change phones or stop using the tool for a while.
My final take after following the full workflow
Debt Payoff Planner & Tracker succeeds because it concentrates on a problem that broad finance apps often bury under too many features. I can begin with a messy set of balances, turn them into a chosen order, carry the plan into real payment accounts, and return to measure progress. The strongest insight is that the app works best as a recurring bridge between intention and action, not as a passive dashboard that I open once and forget.
Its weaknesses are just as clear. Manual updates demand care, projections depend on accurate inputs, and the app cannot solve an affordability crisis or manage every part of personal finance. Those are meaningful boundaries, not reasons to dismiss it. They tell me how to use it responsibly: verify current creditor details, update after payments, review the plan when circumstances change, and seek specialized help when the debt problem is bigger than a repayment schedule.
For someone who wants a focused, motivating debt plan and is prepared to do the necessary follow-through, I think this is a practical choice. It gives structure without overwhelming me with unrelated financial tools. The best reason to use it is not the promise of a perfect forecast, but the steady habit of making one informed extra-payment decision at a time. That makes the free app worth trying, especially for anyone ready to replace vague financial stress with a plan they can actually revisit.
Debt Payoff Planner & Tracker FAQ
What is Debt Payoff Planner & Tracker used for?
Debt Payoff Planner & Tracker is designed to help you organize and manage personal debt in one place. You can enter balances, interest rates, minimum payments, and due dates, then review your progress as you make payments. It can also help compare payoff approaches, such as focusing on smaller balances first or prioritizing debts with higher interest rates, although it does not replace professional financial advice.
Can I use Debt Payoff Planner & Tracker for different types of debt?
Yes, the app can generally be used to track several common forms of debt, including credit cards, personal loans, student loans, medical bills, and other installment accounts. Each debt can usually be added with its own balance, interest rate, payment amount, and schedule. The accuracy of the projections depends on entering current information and updating the account details whenever your lender changes the terms.
Does the app make payments to creditors automatically?
Debt Payoff Planner & Tracker is primarily a planning and tracking tool, not a bank or payment processor. It typically helps you calculate repayment plans and monitor progress, but it does not automatically pay your creditors unless a clearly stated integration is available in the version you use. You should continue making payments through your lender’s official website, app, or another trusted payment method.
What information do I need before setting up my debt payoff plan?
For the most useful results, prepare the current balance, annual interest rate, minimum monthly payment, payment due date, and any known promotional rate or payoff deadline for each account. You may also want to decide how much extra money you can consistently contribute each month. Avoid guessing when possible, because incomplete or outdated figures can make payoff dates and interest estimates less reliable.
Is Debt Payoff Planner & Tracker free to download and use?
The app may be available to download at no initial cost, but some features can depend on the current subscription or in-app purchase model. Advanced tools, unlimited debt accounts, detailed reports, synchronization, or advertising removal may require payment. Before downloading, check the Google Play Store or App Store listing for the latest pricing, trial conditions, renewal terms, privacy information, and supported devices.











